Belgian construction VAT rates: when 0%, 6%, 12% or 21% applies
Choose the right Belgian construction VAT rate (21%, 6%, 12% or reverse charge) by checking building age, use, customer status and 2026 rules.
Construction work in Belgium does not follow a single default VAT rate. Standard Belgian VAT is 21%, and every alternative — 0% co-contractor reverse charge, 6% renovation VAT, or 12% social housing VAT — requires specific legal conditions to be met and documented before the invoice goes out.
Copying last month's VAT code from an earlier quote for the same client is one of the fastest ways to trigger a VAT reassessment. Start from 21%, check the six project facts below, and split mixed jobs line by line so one excluded item never taints the rest of the invoice.
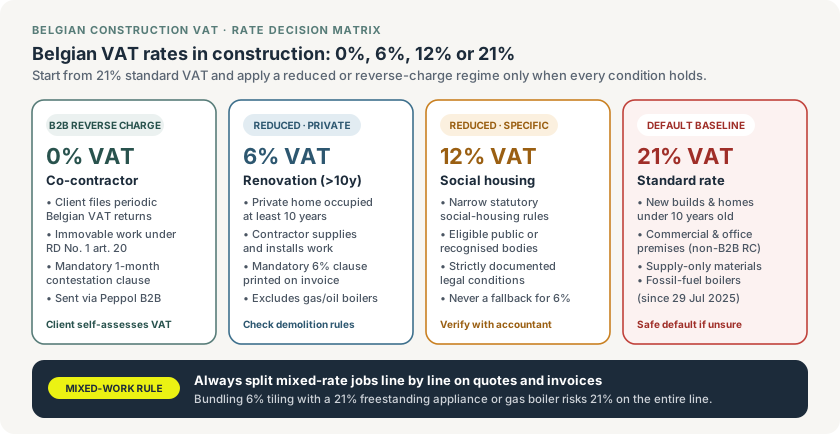
The four Belgian VAT regimes contractors encounter on site — and the boundary rules that separate them.
Six facts to check before picking a VAT rate
| Project check | What to record in the file | Why it changes the rate |
|---|---|---|
| Customer VAT status | Valid Belgian VAT number & periodic filing check | Triggers mandatory B2B co-contractor reverse charge |
| Building age | Year of first occupation (not permit date) | Determines eligibility for the 10-year 6% renovation regime |
| Actual building use | Private, commercial, mixed or social housing | Professional rooms and commercial buildings stay outside 6% |
| Exact work performed | Room-level quote and executed quantities | Separates qualifying immovable work from excluded items |
| Supply vs installation | Whether you both supply and install materials | Supply-only material sales stay at 21% |
| Chargeable timing | Performance, invoice and advance payment dates | Determines VAT return period and any rule cut-off dates |
Never lock a single VAT rate at the customer level. A Belgian architect or business owner can hire you for their commercial office (reverse charge or 21%) and later for their private 1960s residence (6% if all conditions hold).
When 21% standard VAT is the baseline
Apply 21% whenever no specific reduced or reverse-charge regime is fully supported. Common 21% situations include:
- New residential construction outside a qualifying demolition-and-reconstruction scheme;
- Private homes first occupied less than ten years ago;
- Commercial premises, workshops or offices billed to non-VAT-filing clients;
- Material-only sales without installation (tiles, timber, fittings picked up from your yard);
- Items excluded from the 6% renovation regime (swimming pools, garden paths, freestanding appliances);
- Fossil-fuel central heating installations (see below).
Charging 21% is not a penalty — it is the legal baseline. Applying 6% without verifying the building's age and use leaves your business exposed to the 15% VAT shortfall, default interest and administrative fines.
Co-contractor reverse-charge VAT (0% B2B)
When you perform qualifying work on immovable property for a client registered for Belgian VAT who files periodic VAT returns, you do not charge VAT on your invoice. Instead, you invoice at 0% reverse charge (btw verlegd / TVA cocontractant) under Royal Decree No. 1, Article 20, and your client self-assesses the VAT in their own return.
Since January 2023, every Belgian co-contractor invoice must carry the updated mandatory reverse-charge wording stating that the client has one month from receipt to contest the application of reverse charge in writing if they do not file periodic returns. Remember that domestic B2B co-contractor invoices must also be transmitted via Peppol, mandatory in Belgium since 1 January 2026. For the full B2B rules, read our co-contractor VAT breakdown.
6% renovation VAT for private homes over 10 years old
Qualifying renovation, repair and maintenance work supplied and installed in a private dwelling first occupied at least ten years ago qualifies for 6% VAT.
Keep three operational rules tight:
- Use the mandatory invoice statement, not an old paper form: Since 2022, printing the prescribed FPS Finance 6% clause on the invoice replaces the historic signed 6% certificate (giving the homeowner one month to contest in writing). See our full 6% VAT evidence checklist.
- Split mixed-use buildings: If a home includes a professional office or consultation room, allocate clearly by room on the quote and invoice so purely professional spaces remain at 21%.
- Watch fossil-fuel heating installations: Since 29 July 2025, gas and fuel-oil central heating boilers — and components working exclusively with fossil-fuel heating — fall under 21% VAT even in homes over ten years old. The transitional window for older contracts closed on 30 June 2026. Always price fossil boilers on separate lines from non-fossil components such as radiators or underfloor loops.
12% VAT is not a compromise rate
Belgian 12% VAT applies only to narrowly defined statutory regimes — primarily certain qualifying social-housing projects commissioned by recognised social-housing bodies or eligible institutions. It is never a middle ground when a private renovation misses the 10-year threshold for 6%.
Before quoting 12%, identify the exact legal basis, confirm the client's qualifying status in writing and store the supporting declarations in the project folder.
Demolition and reconstruction: separate rules apply
Demolition and reconstruction projects follow their own Belgian VAT regime — distinct from ordinary renovation — with strict rules around building footprint, dwelling status, floor-area ceilings, official FPS Finance declarations and timing. Calling a total rebuild a "deep renovation" on a quote does not make it qualify under the 10-year renovation clause. Check the current FPS Finance forms and confirm with your accountant before signing the contract.
Worked example: splitting a mixed-rate renovation invoice
Suppose you renovate a bathroom in a 1982 private home in Ghent and the homeowner also buys a freestanding tumble dryer through you plus a replacement gas condensing boiler:
| Line item | Scope | VAT rate |
|---|---|---|
| Bathroom demolition, waterproofing, tiling & installed shower | Qualifying supply + install in home >10 years | 6% |
| Replacement gas condensing boiler & flue kit | Fossil-fuel heating component (post-29 July 2025) | 21% |
| Freestanding tumble dryer (delivered only) | Uninstalled movable appliance | 21% |
Putting all three under one line labelled "Bathroom renovation" risks the VAT administration reclassifying the entire lump sum at 21%. Separate lines protect the 6% rate on the eligible works.
Keep VAT consistent from quote to final invoice
VAT mistakes often sneak in between an advance invoice, interim progress billing and extra works agreed via change order tickets. Under Belgium's 2025 VAT chain reform, quarterly VAT returns are due on the 25th of the month following each quarter — clean, line-level VAT coding from day one avoids last-minute credit notes before filing day.
With Enfin invoicing, each quote line carries its VAT treatment straight through to advances, progress statements and final invoices, with mandatory Belgian clauses attached automatically. Compare workflows in Enfin construction software or check pricing.
Official Belgian sources
- FPS Finance: Belgian VAT rates
- FPS Finance: building, renovation and VAT declarations
- FPS Finance: updated VAT rules for fossil-fuel heating installations
General practical reference for Belgian construction work. Software carries your chosen VAT codes and clauses, but the contractor and accountant remain responsible for confirming legal eligibility on each project.
Duty of care for subcontractors in Flanders: what applies from 16 October 2026
Chain liability in Flanders: which documents to request from subcontractors. No passport since 16 Oct 2026, small works excluded. Site checklist inside.