Belgian 30bis withholding checks before paying subcontractors
Run Belgian 30bis tax and social withholding checks before paying subcontractors: 2026 self-employed rules, percentages, €7,143 cap and proof.
Paying a Belgian construction subcontractor in full when they carry unpaid tax or social security debts is one of the costliest administrative mistakes a contractor can make. Under Belgium's 30bis withholding obligation (inhoudingsplicht / obligation de retenue), the paying contractor must check the subcontractor's official status right before releasing payment, withhold the prescribed percentage if a debt shows up, and remit that portion directly to the Belgian authorities.
Skip the check and pay 100% anyway, and your company can be held jointly liable for the subcontractor's unpaid debts — plus an administrative surcharge equal to the amount you failed to withhold.
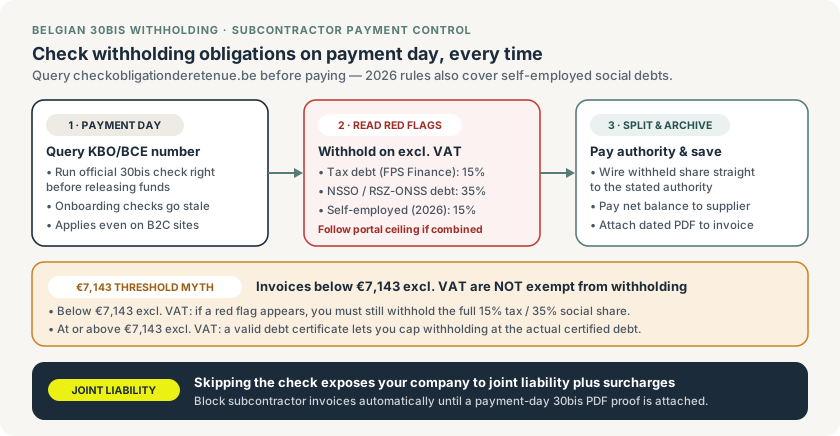
The payment-day 30bis check, the 2026 percentages (including self-employed social debts) and the €7,143 certificate rule.
Who must run the 30bis check — and who does not
The obligation applies to any principal or contractor paying another party for covered immovable works (werken in onroerende staat / travaux immobiliers) in Belgium.
Two points trip up smaller firms every month:
- Private homeowners vs B2C contractors: A private individual hiring a builder strictly for their own home is outside the withholding rule. However, the contractor who hires a plasterer, roofer or electrician as a subcontractor on that same private renovation is fully subject to 30bis checks.
- No small-company exemption: Whether you subcontract a €1,200 bricklaying job or a €90,000 HVAC package, the check applies based on the activity and business relationship — not on company size.
What changed in 2026: self-employed social debts included
Historically, Belgian contractors checked two buckets: federal tax debts (FPS Finance) and employer social security debts (NSSO / RSZ / ONSS). In 2026, the official Belgian withholding framework expanded for immovable works to include qualifying self-employed social security debts (RSVZ / INASTI).
An internal checklist that still looks only at employer RSZ/ONSS and FPS Finance status is now outdated — especially when you regularly work with solo self-employed subcontractors. Always consult the unified official portal (checkobligationderetenue.be) and follow the exact result displayed for all applicable authorities.
Withholding percentages and the €7,143 myth
All withholding percentages are calculated on the invoice amount excluding VAT (which in Belgian construction subcontracting is normally already invoiced at 0% under co-contractor reverse-charge VAT).
| Debt flagged by official portal | Standard withholding rate | Authority paid |
|---|---|---|
| Federal tax debt | 15% of invoice excl. VAT | FPS Finance |
| Employer social security debt (NSSO / RSZ-ONSS) | 35% of invoice excl. VAT | NSSO (RSZ / ONSS) |
| Self-employed social debt (2026 immovable works rule) | 15% of invoice excl. VAT | Relevant social authority per portal instructions |
| Combined debts | Portal-calculated split up to the statutory combined ceiling | Follow exact split & structured reference shown |
Watch out for the €7,143 misunderstanding. Many contractors wrongly believe invoices below €7,143 excluding VAT are exempt from withholding. They are not.
- Below €7,143 excl. VAT: If the portal shows a red status, you must withhold the full applicable percentage (e.g. 15% tax and/or 35% social) immediately.
- At or above €7,143 excl. VAT: The subcontractor can provide a time-limited official debt certificate showing the exact balance owed. If the certified debt is lower than 15% (or 35%) of the invoice, you may limit your withholding to that lower certified amount.
Quick worked example
Your electrician submits a €10,000 (excl. VAT) invoice for a commercial fit-out in Antwerp. On payment day, the official portal shows no social debt (green) and a tax debt (red), and the subcontractor provides no debt certificate:
- Withhold 15% = €1,500 and transfer it to FPS Finance using the structured reference provided by the portal.
- Pay the remaining €8,500 directly to the electrician.
- Archive the dated PDF query result and both bank transfers against that specific purchase invoice.
Six-step payment-day routine that prevents Friday mistakes
Checking a subcontractor once during onboarding is worthless three months later: debt statuses update continuously, and a subcontractor who was green in March can turn red by May. Build the check into the payment run itself:
- Confirm the enterprise number (KBO/BCE) on the incoming Peppol purchase invoice matches your supplier record and purchase order.
- Run the official check on payment day at checkobligationderetenue.be via a trusted bookmark.
- Read all authority flags (tax, NSSO and self-employed social debt) — never assume a red box automatically equals 35%.
- Route red or unclear results to an exception queue instead of releasing them in the standard payment batch.
- Execute split payments carefully for partial settlements, credit notes or disputed invoices so every remittance ties back to the exact excl.-VAT base.
- Attach the dated PDF proof to the invoice transaction — not just to a generic supplier folder — recording the enterprise number, timestamp, calculation and reviewer.
Protect your project margin and cash flow
Unexpected joint liability can wipe out the margin on an entire site overnight. Keep subcontractor purchase invoices, approval trails and cost-to-complete commitments in one structured flow alongside your margin per project tracking. Explore how Enfin construction software centralises supplier records, invoicing and site administration, or view Enfin pricing.
Official Belgian sources
- Official verification portal: checkobligationderetenue.be
- Belgian Social Security: 30bis withholding obligation overview
- Belgian Social Security: consultation, percentages and invoice withholding
- FPS Finance: tax withholding obligation
General operational guidance for Belgian construction firms. Confirm complex chain-liability or multi-authority cases with your accountant or legal adviser.
Belgian site-safety cascade: who checks each subcontractor in the chain?
Map safety duties through a Belgian construction subcontractor chain and keep contracts, evidence, owners and escalation separate from attendance records.
Duty of care for subcontractors in Flanders: what applies from 16 October 2026
Chain liability in Flanders: which documents to request from subcontractors. No passport since 16 Oct 2026, small works excluded. Site checklist inside.
A heat-pump quote with several subcontractors: name the main point of contact
Create a contact and responsibility sheet for a heat-pump project involving heating, electrical and building contractors, with clear approval boundaries.