Make Your Invoicing Process Peppol-Ready and Auditable
Test structured invoice data, exceptions, delivery evidence, corrections and ten-year archiving so your Belgian e-invoicing process remains reliable.
A Peppol-ready process does more than produce one successful test invoice. It keeps customer data accurate, validates every structured document, makes failed deliveries visible, preserves corrections and retains the original invoice in a form that can be retrieved later.
Test the source data first
Review company details, VAT numbers, customer identifiers, payment data, product tax settings and invoice sequences before switching transmission on. Structured validation exposes inconsistent data that a PDF may have hidden.
Assign ownership for master-data changes. A corrected customer address should update future documents without silently rewriting an invoice that was already issued.
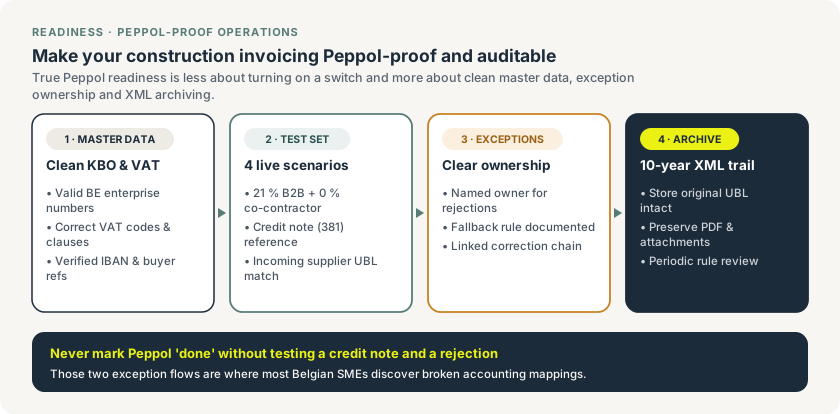
Test at least four real scenarios before sign-off: standard 21 %, co-contractor 0 %, credit note (381) and incoming supplier bill.
Build a representative test set
One simple invoice proves very little. Use anonymised or test data to cover:
- a standard Belgian B2B invoice;
- more than one VAT rate where appropriate;
- an advance or progress invoice;
- a credit note linked to an earlier invoice;
- a customer reference and permitted attachment;
- an invalid identifier that should fail clearly.
Confirm both what the sender sees and what appears in the receiving system.
Define exception ownership
Decide who handles a validation failure, unknown receiver, duplicate, rejected document or customer dispute. The system should show an actionable status rather than leaving an invoice marked merely as “sent”.
Create a small exception queue with owner, next action and resolution. Avoid fixing a rejection by editing the original issued document in place.
Preserve correction links
Credit notes and replacement documents need an explicit relationship to the original invoice. Keep numbering, dates, reasons and delivery evidence. The accounting export and customer record should tell the same story.
Run a correction test before launch; it is much easier to learn the workflow without a customer waiting.
Archive the right objects
Keep the structured invoice, a legible representation, relevant attachments and the transmission or correction trail. FPS Finance states a ten-year retention period for invoices and VAT accounting documents. Test search and restore, not only storage.
Limit access by role and document how the archive remains available if the software provider changes.
Review scope and rules periodically
The official B2B FAQ is updated as practical questions are clarified. Date your internal decision rules and review them with the accountant when the company’s VAT status, markets or software change.
Do not mix the current structured e-invoicing obligation with future electronic reporting. The official portal treats them as separate phases.
Use a readiness sign-off
Before production, ask the process owner, administrator and accountant to confirm:
- scope decisions and exceptions are documented;
- sender and receiver data are verified;
- representative documents pass validation;
- delivery failures are visible and owned;
- credit notes preserve the audit trail;
- the structured original and legible view can be retrieved;
- staff know where to find current official guidance.
That sign-off is more meaningful than a logo or a checkbox labelled “Peppol compatible”.
Peppol e-invoicing in Belgium: step-by-step setup for contractors
Follow five practical steps for Belgian Peppol B2B e-invoicing: check scope, clean KBO data, test sending and receiving, and handle credit notes.
Mandatory Peppol e-invoicing in Belgium (2026): scope, rules and exceptions
Belgium's B2B Peppol e-invoicing mandate has been live since 1 January 2026. Check who is in scope, which exceptions apply and how contractors stay compliant.
Construction quote assumptions and exclusions: make the scope executable
Turn assumptions, provisional choices and exclusions in a Belgian construction quote into clear ownership before acceptance.