How to track project margin per job in Belgian construction
Track real-time gross and net margin per construction site across labour, materials, subcontractors and overhead—spot cost overruns before handover.
Your year-end accounts might show a healthy 9% operating profit across the whole company while hiding an uncomfortable truth: two bathroom and extension jobs made 18%, and a third renovation quietly lost €6,500 because extra crew hours and subcontractor variations were never billed back. Company-wide profit tells you what happened last quarter; margin per project tells you which sites, trades, and client types actually make money while you can still act on it.
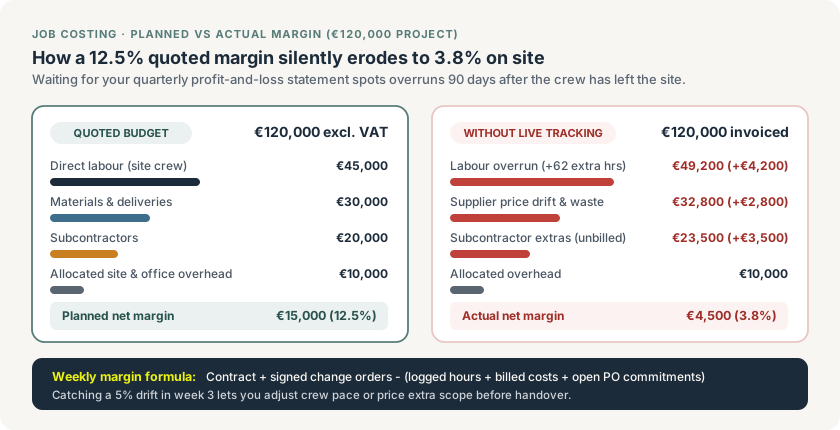
How a budgeted 12.5% net margin on a €120,000 project shrinks to 3.8% when extra site hours, supplier drift, and unbilled extras go untracked.
Gross project margin vs net project margin
Before setting up tracking sheets or job-costing software, separate two figures that Belgian contractors often mix up:
- Gross project margin (site contribution) = Contract revenue (quoted price + signed change orders) minus direct job costs: site labour (at full employer cost, not gross wage), job materials, plant hire, and subcontractors.
- Net project margin = Gross project margin minus allocated indirect overhead (vans, workshop rent, insurance, office staff, software, accounting).
Tracking only direct costs makes every job look profitable until general overhead eats the surplus at year-end. Including a realistic overhead allocation — aligned with your contractor hourly rate — shows true site profitability.
Worked example: quoted budget vs actual site outcome
Look at a fictional €120,000 Belgian structural renovation (all figures excluding VAT):
| Cost category | Quoted budget | Actual outcome | Variance |
|---|---|---|---|
| Contract revenue (excl. VAT) | €120,000 | €120,000 | €0 |
| Direct site labour (PC 124 loaded cost) | €45,000 | €49,200 | +€4,200 |
| Materials & site deliveries | €30,000 | €32,800 | +€2,800 |
| Subcontractors | €20,000 | €23,500 | +€3,500 |
| Allocated overhead (vans, supervision, admin) | €10,000 | €10,000 | €0 |
| Total project cost | €105,000 | €115,500 | +€10,500 |
| Net project margin | €15,000 (12.5%) | €4,500 (3.8%) | -€10,500 |
Nothing catastrophic happened on this site. Sixty-two unbudgeted labour hours (+€4,200), a 9% supplier price drift plus extra skip hire (+€2,800), and one unbilled subcontractor variation (+€3,500) wiped out 70% of the planned profit.
Why posted supplier invoices are always too late
Waiting until your accountant books incoming Peppol supplier invoices at the end of the quarter means you only see a cost overrun weeks after the scaffolding has come down. Live margin tracking requires committed costs alongside paid bills:
- Daily site hours: Log crew hours by project and phase through construction time tracking, priced at true loaded hourly cost (including RSZ/ONSS, holiday pay, and PC 124 stamps).
- Open purchase orders and subcontractor awards: The moment you issue a €14,000 timber order or sign a €9,000 plastering subcontract, deduct it from the remaining job budget — even if the invoice arrives 45 days later. Using structured construction purchase orders makes those commitments visible immediately.
- Signed extra work: Add approved change order tickets to the contract revenue column only once signed so your live margin never relies on wishful thinking.
Combine billed costs, open commitments, and an honest estimate of remaining work using cost-to-complete tracking. That single view tells you in week 3 — not week 14 — whether a job is drifting off course.
Four early-warning triggers worth setting on every site
Pick clear numerical triggers so project reviews take ten minutes instead of turning into blame sessions:
- Labour burn > physical progress by 10%+: You have spent 60% of the labour budget while only 45% of the phase is complete. Inspect site access, crew mix, or hidden substrate issues immediately.
- Unbilled extras accumulating: Any extra work exceeding €250–€500 without a signed change order stops until priced and approved.
- Material invoice > purchase order price: Flag supplier surcharges or extra pallet deliveries on arrival rather than absorbing them silently.
- Net projected margin drops below your floor (for example, below 8%): Review remaining scope, subcontractor quotes, and schedule before ordering the next phase.
Turn completed-job data into sharper quotes
Once you have real margin figures across ten or fifteen completed Belgian jobs, patterns jump off the screen:
- Job types: Full bathroom rebuilds may consistently clear 16%, while small multi-trade punch-list renovations sink to 4% because of coordination overhead.
- Travel radius: Sites more than 45 minutes from your depot often burn two unpaid van hours a day unless travel is priced explicitly.
- Subcontractor reliability: A slightly cheaper subcontractor whose delays force your own crew to return twice costs far more in lost margin than a reliable partner.
Feed those post-mortem numbers straight back into your unit rates and estimating workflow. Remember that healthy project margin also depends on healthy construction cash flow: billing milestones promptly via Peppol (mandatory for Belgian B2B since 1 January 2026) keeps profit from turning into uncollected debt. Always verify VAT treatment separately on the FPS Finance VAT portal so margin calculations stay strictly excluding VAT.
Start tracking this week in four steps
- Pilot on two active jobs rather than rewriting past history — assign every purchase invoice, PO, and crew hour a clear Project ID.
- Review budgeted vs actual + committed costs every Friday in a 15-minute stand-up with your foreman or project lead.
- Log every scope change before execution so revenue rises alongside cost.
- Run a 20-minute close-out review after handover and adjust your quoting templates for the next similar project.
See how Enfin construction software links quotes, purchase orders, site hours, and live project profitability in one system, or explore Enfin estimating.
How to Track Project Costs: Labor, Travel and Fixed Expenses
Practical guidance for Belgian construction SMEs on recording labor hours, travel mileage and overhead per project to improve cost control and profitability.
Forecast final job margin with open purchase orders
Use a Belgian contractor’s worked example to reconcile posted costs, outstanding orders and the cost of remaining work before handover.
Why did the job margin fall? Separate price, quantity and labour variances
A worked construction example separating material price changes, excess consumption and extra labour hours without double counting.