Belgian reverse-charge VAT (co-contractor) for construction invoices
Check both legal tests before issuing a 0% Belgian co-contractor VAT invoice: immovable work, periodic VAT filers, the 2023 1-month clause and Peppol codes.
Removing VAT from a Belgian construction invoice is not optional when the legal conditions are met — and applying 0% reverse charge when those conditions are not met leaves you exposed to backdated VAT, penalties, and interest during an audit. Under Royal Decree No. 1, Article 20 (btw medecontractant / TVA cocontractant), VAT accounting shifts from the contractor to the customer only when both the nature of the work and the customer's Belgian VAT status qualify.
Seeing a Belgian VAT number or a construction NACE code in the KBO/BCE register is never enough on its own. Run a structured two-gate check before issuing the invoice.
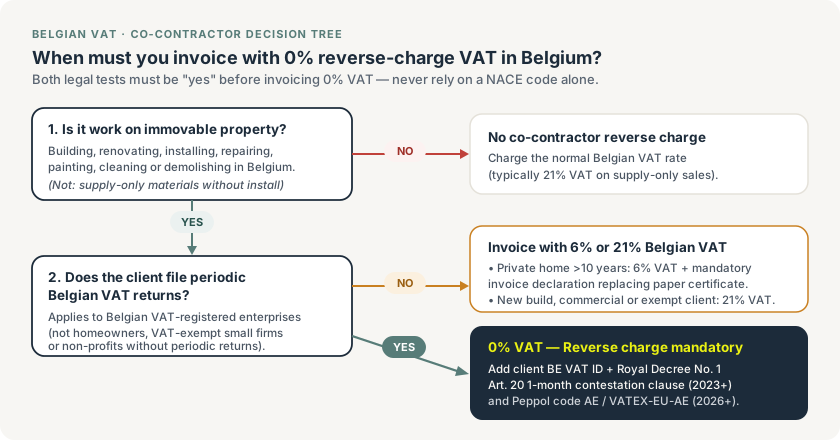
Two-gate check for Belgian co-contractor reverse-charge VAT, including the mandatory 1-month contestation clause and 2026 Peppol tax code.
Gate 1: Verify the actual work on immovable property
Start with what is contractually supplied and installed. Belgian reverse charge covers work in immovable state (werk in onroerende staat / travail immobilier) carried out on a building in Belgium — building, renovating, finishing, installing fixed equipment, repairing, cleaning, or demolishing.
It does not cover standalone material sales without installation, equipment rental without operator, or pure consultancy and design fees billed separately. Mixed contracts (for example, supplying loose appliances alongside fitted cabinetry) require careful line separation. Describe the exact work on both quote and invoice; a vague line reading "site works completed" invites questions from FPS Finance and makes audits painful to defend.
Gate 2: Confirm the customer files periodic Belgian VAT returns
A valid Belgian VAT number is only half the story. Reverse charge applies only if the customer is established in Belgium (or registered with a Belgian fiscal representative) and files periodic monthly or quarterly Belgian VAT returns.
That excludes several customer types that still carry a KBO/BCE or VAT number:
- Private homeowners (bill at 6% if the private residence is over 10 years old and qualifies under Belgian construction VAT rates, or 21% otherwise);
- Small businesses under the Belgian VAT exemption scheme (kleine onderneming / franchise TVA) — they hold a BE VAT number but do not file periodic VAT returns;
- Fully VAT-exempt organisations such as medical practices, schools, or non-profits (vzw / asbl) that do not submit periodic VAT returns.
For a sole trader working from a mixed-use home-office who does file periodic VAT returns, reverse charge can still apply even when work touches part of the building — confirm the exact split with your accountant and keep written confirmation on the project file.
Why NACE codes alone are an unsafe automation rule
KBO/BCE NACE codes starting with 41, 42, or 43 show registered business activities, not how a specific invoice must be taxed. Businesses add or drop activities without updating NACE codes, hold mixed exempt/taxable activities, or buy materials without installation. Treating a NACE code as an automatic trigger for 0% VAT causes silent compliance errors. Use KBO/BCE data as a review prompt, never as the final tax decision.
Mandatory wording: the 1-month contestation clause (since 2023)
When co-contractor reverse charge applies, never copy an outdated one-line "Btw verlegd" stamp from a ten-year-old template. Since 1 January 2023, Belgian law requires a specific statutory notice on the invoice informing the client that VAT is shifted to them and giving them one month from receipt of the invoice to contest the reverse-charge treatment in writing if they do not file periodic Belgian VAT returns.
In English (check the exact official Dutch or French legal text with your accountant for the invoice language you issue in), the notice communicates:
Reverse charge: in the absence of a written contestation within one month of receipt of this invoice, the customer is deemed to acknowledge that they are a taxable person required to file periodic VAT returns. If that condition is not met, the customer is liable for the payment of VAT, interest and penalties due in respect of that condition.
Why this clause matters so much: when properly included, it protects the contractor from VAT liability if a client with a Belgian VAT number turns out to be VAT-exempt and fails to notify you within one month. Keep the official Dutch (Btw verlegd — Bij gebrek aan schriftelijke betwisting...) or French (Autoliquidation — En l'absence de contestation par écrit...) version locked inside your invoice template.
Peppol B2B codes and VAT-return boxes (2026)
Because structured B2B e-invoicing over Peppol has been mandatory in Belgium since 1 January 2026, your invoicing software must also map co-contractor invoices accurately inside the UBL 2.1 XML file:
- VAT category code:
AE(VAT reverse charge) with tax percentage0; - Exemption reason code:
VATEX-EU-AEalong with the statutory Royal Decree No. 1 Art. 20 / 1-month contestation text; - Customer VAT ID: valid Belgian
BE0...identifier matching the Peppol participant.
In your periodic Belgian VAT return, supplier and customer report co-contractor invoices in distinct boxes (typically box 45 for the contractor's outgoing co-contractor turnover, while the buyer reports the base and self-assesses VAT in their own return). Always test one live invoice and one credit note with your accountant and verify current return rules against the FPS Finance periodic-return guidance.
Six-step review before releasing a 0% invoice
| Step | What to verify |
|---|---|
| 1. Scope | Work qualifies as immovable construction, installation, maintenance, or demolition in Belgium. |
| 2. Customer status | Valid BE VAT number and confirmation that the client files periodic VAT returns. |
| 3. Mandatory wording | Current Royal Decree No. 1 Art. 20 notice including the 1-month contestation clause. |
| 4. Peppol UBL tags | Category AE, 0% rate, VATEX-EU-AE, and matching customer VAT ID. |
| 5. Project evidence | Save VAT validation and any client confirmation in the project folder. |
| 6. Subcontractor chain | If you are the main contractor paying subcontractors, pair VAT checks with 30bis withholding checks. |
Fixing an incorrect VAT invoice cleanly
If you charged 21% by mistake on a qualifying reverse-charge job — or applied 0% to an exempt client — never overwrite or delete the original invoice. Issue a formal credit note referencing the original invoice number and send a corrected replacement invoice via Peppol so both your books and your customer's VAT return stay aligned. For complex mixed buildings or foreign principals, consult your accountant and check the FPS Finance VAT information pages before sending.
Keep co-contractor templates, 6% renovation clauses (see 6% VAT certificate rules), and validated Peppol UBL codes in one place with Enfin invoicing, or view pricing.
A B2C contractor still needs to receive Belgian supplier invoices through Peppol
Understand why consumer-facing contractors still need structured supplier-invoice intake and organise the incoming construction-cost workflow.
Advance invoices and progress billing in Belgian construction
Structure Belgian construction advance invoices and progress bills cleanly: sample schedule, Breyne Act 5% cap, VAT timing and Book XIX rules.
Construction retention tracking in Belgium: keep invoices and guarantees distinct
A practical project-control workflow for Belgian contractors tracking retained amounts, invoice balances, acceptance stages and release evidence.